Outlook · 2026-06-15
Freight and CFR dislocation reshape H1 2026 delivered economics
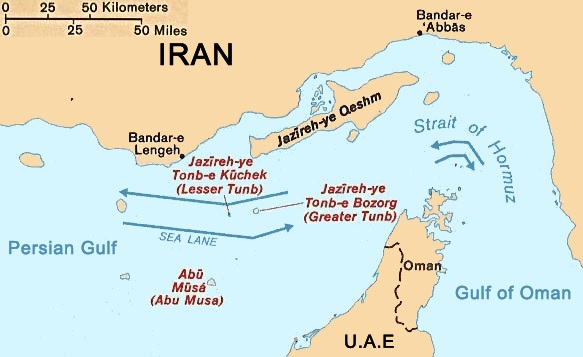
Second-quarter 2026 saw freight become a first-order price component. An open H1 2026 market table (call2supply) showed FOB Middle East rising from about $525/t in February toward about $900/t in June, CFR China from about $547/t toward about $1,075/t, and Middle East-China freight from roughly $26-27/t to $161-170/t. SMM described CIF Indonesia quotations into roughly $1,100-1,250/mt by mid-May. Phosphate producers faced margin compression; SSY/CRU commentary noted production cuts such as OCP’s reported 2Q26 response. Alternative origins included Vancouver, limited Red Sea workarounds, and Central Asian rail into western China. UNCERTAIN: how much of the freight spike was war-risk premium versus vessel scarcity that persists after Hormuz normalization. Second-quarter 2026 made freight a first-order component of delivered sulfur cost. Open H1 tables showing Middle East-China freight from about $26-27/t in February to about $161-170/t in June sit beside FOB Middle East climbing toward about $900/t and CFR China toward about $1,075/t in the same commentary. SMM’s mid-May CIF Indonesia range near $1,100-1,250/mt captured SE Asia’s squeeze. Phosphate producers faced margin collapse; SSY/CRU commentary on production cuts, including OCP’s reported 2Q26 response, shows demand destruction as a clearing mechanism. Alternative origins. Vancouver, limited Red Sea workarounds, Central Asian rail into western China. could not fully replace Gulf seaborne share. UNCERTAIN remains how much of the freight spike was temporary war-risk premium versus lasting vessel scarcity after transit resumes.
Key points
- Open H1 table: ME-China freight ~$26-27/t (Feb) to ~$161-170/t (Jun).
- CFR China ~$547→~$1,075/t; FOB ME ~$525→~$900/t in same report.
- SMM mid-May: CIF Indonesia ~$1,100-1,250/mt range in that commentary.
- Demand destruction signals in phosphate and some metals leaching.
- UNCERTAIN: H2 mean reversion in Gulf freight if security risk eases.
Sources
- 2026 Sulphur Price Analysis (call2supply)
- SMM analysis after sulfur breaks through $1,200
- Sulphur Shock Cascades through Dry Bulk Markets (SSY)
Public reference summary. Weekly PRA assessments require a commercial license. Not investment advice.
Public-source summary. Not investment advice. Unsubscribe from the email edition: reply UNSUBSCRIBE or email outlook@sulfurwire.com.