Outlook · 2021-09-15
Supply tightness and elevated dry-bulk freight into autumn 2021
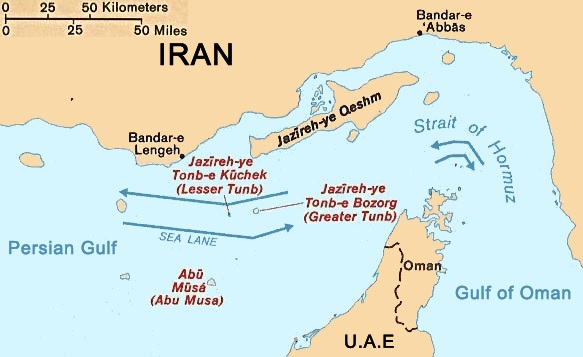
Third-quarter 2021 solidified a tighter global sulfur balance as refinery utilization improved unevenly and phosphate buyers competed for solid cargoes. An Argus Sulphur sample report dated 23 September 2021 showed FOB Vancouver contract indications near $184-194/t for 3Q 2021 alongside Middle East FOB spots near $189-191/t, with large-vessel Middle East-South China freight cited around $44-46/t. Tampa 3Q 2021 molten was listed near $195/lt in that same public sample sheet. Elevated dry-bulk rates after the 2021 freight rebound raised delivered costs into China, India, and Brazil even when FOB was only moderately firm. Canadian exporters faced the dual constraint of forming and rail capacity inland and vessel programs on the Pacific. UNCERTAIN: how much of the September 2021 Vancouver-Asia delivered premium reflected bunker and vessel scarcity versus sulfur-specific tightness. Autumn 2021 sits at the hinge between pandemic recovery and the 2022 spike. The Argus sample sheet’s juxtaposition of Vancouver contract bands near $184-194/t, Middle East spots near $189-191/t, and Tampa near $195/lt shows how tightly hubs had converged in absolute level even as freight differentiated delivered cost. Large-vessel Middle East-South China freights near $44-46/t meant Asian buyers paid a substantial logistics premium on Gulf origins, while smaller Handymax parcels cost still more. Canadian Pacific stems competed on open-ocean routing without a Hormuz chokepoint, but inland rail and forming still set the pace of offer volumes. Dry-bulk strength across the wider commodity complex in 2021 raised the opportunity cost of holding vessels for sulfur versus grain or coal. That freight layer would intensify again in May 2022 when Vancouver-China sulfur freights printed in the low-to-mid $40s/t on a public Argus sample, confirming that 2021’s elevated logistics costs were a prelude rather than a one-off.
Key points
- Argus sample (23 Sep 2021): FOB Vancouver 3Q contract band ~$184-194/t; Tampa 3Q ~$195/lt.
- Same sample: ME-South China large-vessel freight ~$44-46/t.
- Global dry-bulk rebound in 2021 lifted sulfur ocean cost components.
- Canadian solid export remained the Pacific alternative to Middle East granular.
- UNCERTAIN: average Q3 2021 Vancouver-China sulfur freight (no continuous open index).
Sources
Public reference summary. Weekly PRA assessments require a commercial license. Not investment advice.
Public-source summary. Not investment advice. Unsubscribe from the email edition: reply UNSUBSCRIBE or email outlook@sulfurwire.com.