Outlook · 2021-12-15
Year-end firmness with Alberta inventory as export buffer
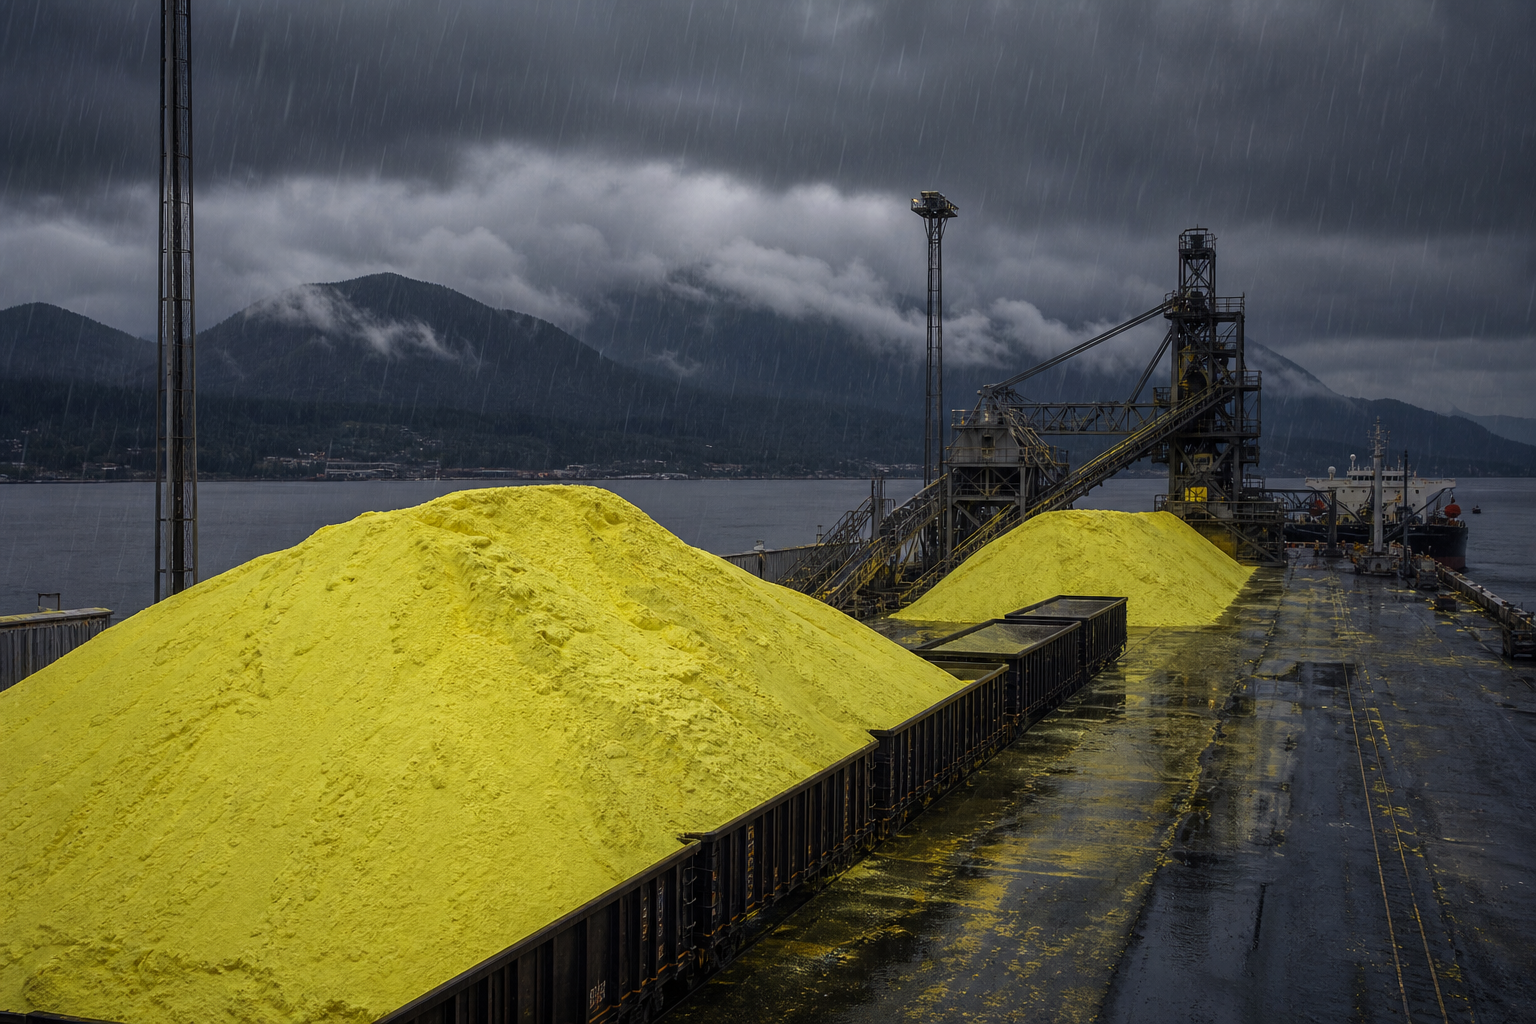
Fourth-quarter 2021 kept Tampa molten contracts near $183/lt per USGS, ending a year that began near $69/lt. The path reflected supply issues after pandemic refining cuts more than a permanent demand boom. Vancouver’s full-year 2.29 Mt sulphur throughput left Canadian marketers with unused inland forming and terminal capacity heading into 2022. Alberta block and plant inventories remained the structural buffer: when Pacific netbacks failed to cover remelt, rail, forming, and terminal costs often cited above $150/t in later Argus commentary, producers poured to block. By late 2021 the market was positioned for a much sharper 2022 spike if phosphate demand and logistics stress intensified together. UNCERTAIN: precise year-end 2021 AER Alberta inventory tonnes; industry commentary later placed multi-year lows only in 2025. Closing 2021 with Tampa near $183/lt after an early-year print near $69/lt compressed a full mini-cycle into twelve months. The move validated USGS language about supply-driven firmness without yet matching the April 2022 extremes. Vancouver’s 2.29 million tonne sulphur year left headroom in terminals and inland forming that 2022-25 would fill. Alberta’s block inventory functioned as the provincial battery: pour when netbacks fail, remelt when FOB covers the export stack often later cited above $150/t. That optionality is why Canadian balances cannot be read from Claus nameplate alone. Heading into 2022, phosphate restocking risk, residual refining tightness, and geopolitical shocks around energy trade were all latent. The public data stack available to open researchers. USGS Tampa summaries, Port of Vancouver sulphur, and AER inventory products. already framed the market as one that could reprice quickly if demand and logistics stress arrived together.
Key points
- USGS: Q4 2021 Tampa remained ~$183/lt after summer peak path.
- Vancouver 2021 sulphur 2.29 Mt set a low base before 2022-25 volume growth.
- Alberta stockpile economics: pour when export chain costs exceed FOB.
- Stage set for 2022 volatility as fuel demand and phosphate cycles overlapped.
- UNCERTAIN: end-2021 Alberta provincial stock versus May 2019 reference lows cited later.
Sources
- USGS Mineral Commodity Summaries 2022 . Sulfur
- Alberta sulfur inventories fall as exports climb (Argus)
Public reference summary. Weekly PRA assessments require a commercial license. Not investment advice.
Public-source summary. Not investment advice. Unsubscribe from the email edition: reply UNSUBSCRIBE or email outlook@sulfurwire.com.