Outlook · 2026-03-15
2026 supply shock begins: Hormuz closure and stranded cargoes
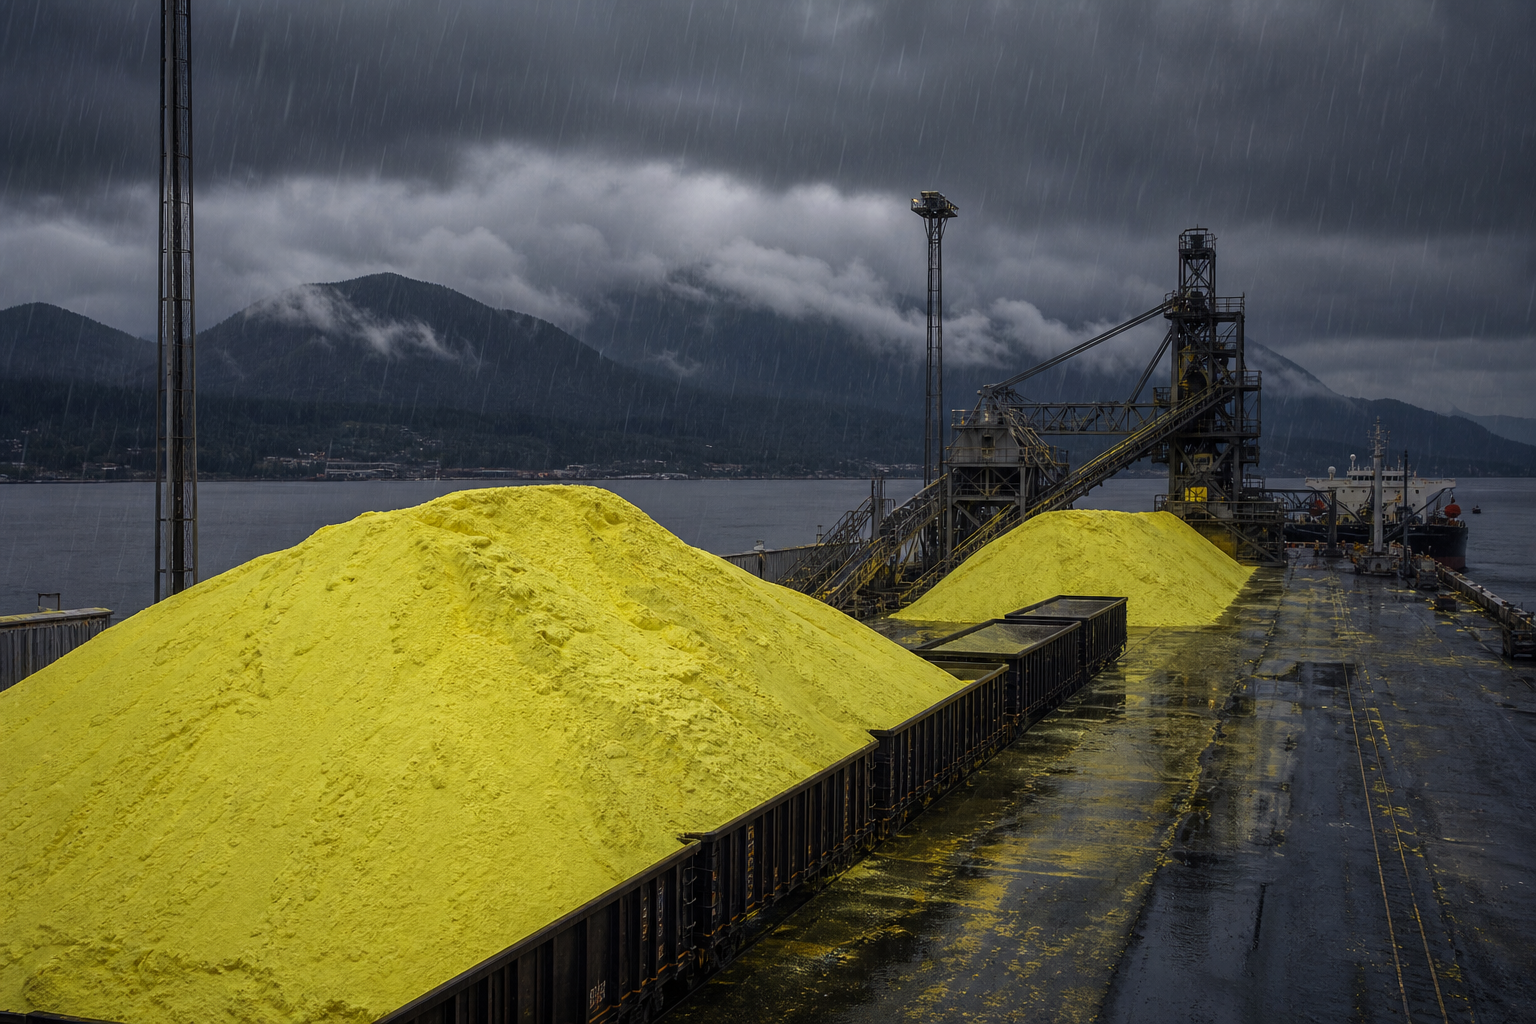
On 28 February 2026, open trade analytics (Kpler) dated the Strait of Hormuz closure to commercial dry bulk traffic, immediately disrupting Middle East sulfur loadings that had supplied roughly 45-50% of seaborne trade. SMM and other open reports described stranded loaded sulfur in the Gulf on the order of 0.8-1.0 Mt and sharp drops in Middle East-China vessel counts. Canadian customs exports of 1.24 Mt in January-March 2026 and FOB Vancouver rising from about $492/mt early year toward $680-720/mt featured in SMM’s May analysis. Vancouver was framed as an unconstrained Pacific alternative, though rail and forming saturation limited upside tonnes. Russia’s sulfur export restrictions compounded the dual-supplier shock. UNCERTAIN: exact monthly Middle East export shortfall in Mt during March 2026; CRU later cited >1.0 Mt/month export declines after conflict onset. First-quarter 2026 opens the supply-shock chapter. Kpler dated Hormuz closure to commercial dry bulk at 28 February 2026, immediately disrupting a region that had supplied roughly 45-50% of seaborne sulfur. Stranded loaded cargoes on the order of 0.8-1.0 Mt in open estimates, sharp drops in Middle East-China vessel counts, and CRU’s later note of monthly export declines above 1.0 Mt describe a corridor failure rather than a mild basis move. Canadian customs exports of 1.24 Mt in January-March and FOB Vancouver rising from about $492/mt toward $680-720/mt in SMM’s May recounting show the Pacific alternative repricing fast. Rail and forming saturation capped how many incremental tonnes Canada could offer. Russia’s export restrictions removed a second major supplier. Byproduct inelasticity meant prices could not summon new Claus plants within the quarter.
Key points
- Kpler: Hormuz closed to commercial dry bulk 28 Feb 2026.
- SMM: Q1 2026 Canadian exports 1.24 Mt; FOB Vancouver ~$492 toward $680-720/mt.
- Middle East historically ~45%+ of seaborne sulfur; China heavily exposed.
- Byproduct inelasticity: price cannot quickly raise Claus output.
- UNCERTAIN: stranded cargo tonnes and restart lag once transit resumes.
Sources
- Sulphur & sulphuric acid in 2026 (Kpler)
- SMM analysis after sulfur breaks through $1,200
- Sulphur market update (BC Insight / CRU, Jul 2026)
Public reference summary. Weekly PRA assessments require a commercial license. Not investment advice.
Public-source summary. Not investment advice. Unsubscribe from the email edition: reply UNSUBSCRIBE or email outlook@sulfurwire.com.